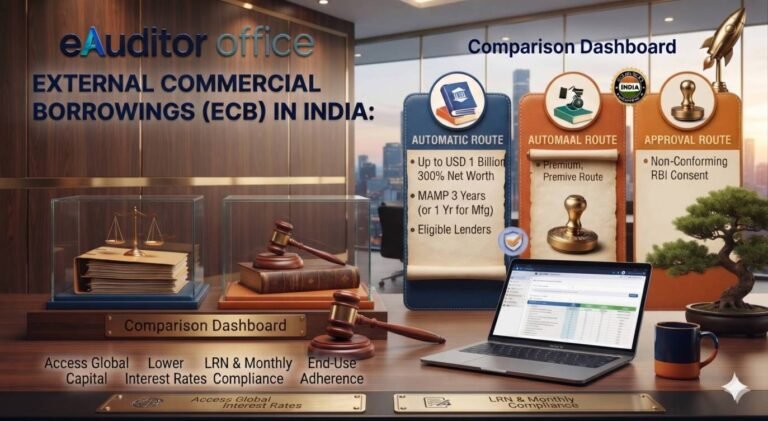
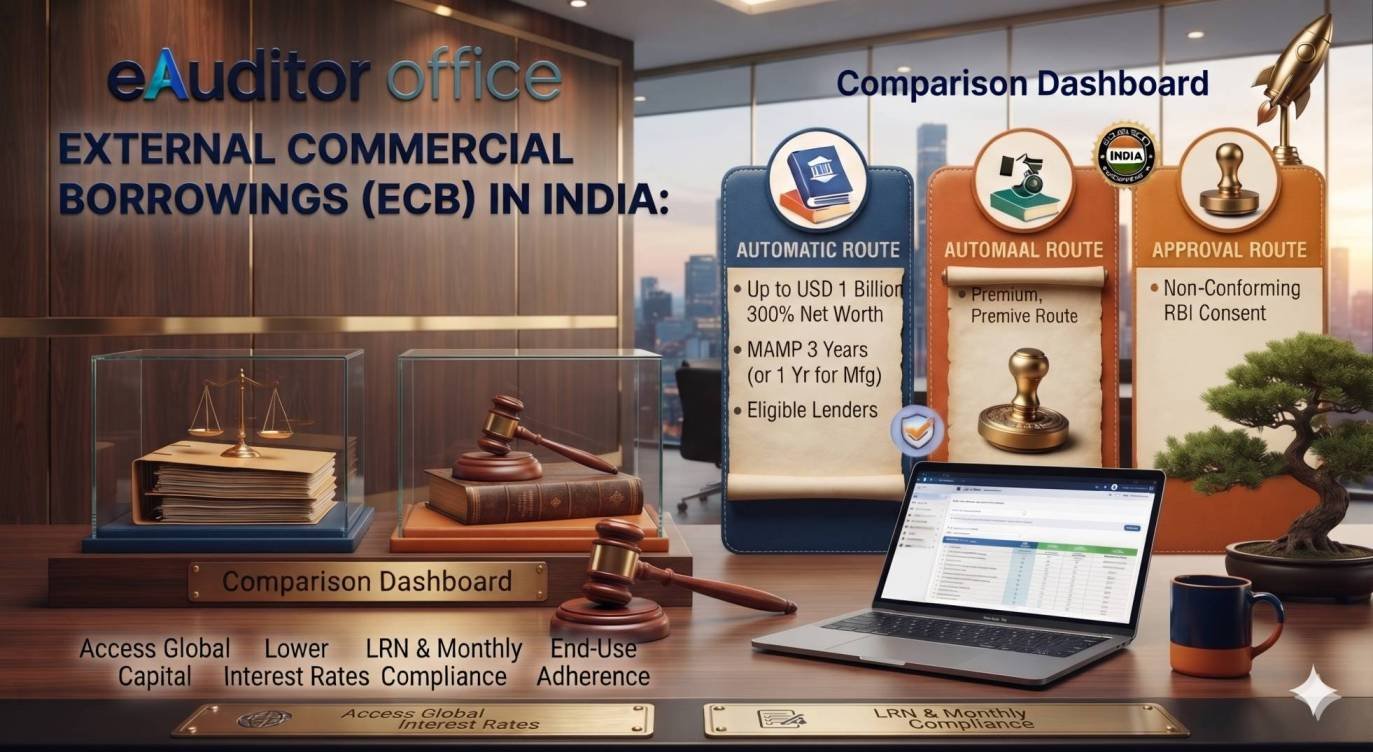
For Indian businesses looking to diversify their funding sources, External Commercial Borrowings (ECB) provide access to global capital pools—often at competitive interest rates and longer tenures than domestic debt. Governed by the Foreign Exchange Management Act, 1999 (FEMA) and regulated by the Reserve Bank of India (RBI), the ECB framework, including the rationalized Foreign Exchange Management (Borrowing and Lending) (First Amendment) Regulations, 2026, sets clear rules on who can borrow, how funds may be deployed, and how transactions must be reported.
Whether you are a founder, CFO, or compliance officer evaluating cross-border debt, this guide covers borrower and lender eligibility, maturity and borrowing limits, end-use restrictions, and the step-by-step Form ECB filing process. For dedicated support with structuring, documentation, and filings, explore External Commercial Borrowings (ECB) Compliance services at eAuditor Office.
What Are External Commercial Borrowings (ECB)?
External Commercial Borrowings are commercial loans raised by eligible resident entities in India from recognized non-resident lenders. ECBs can be raised in either Foreign Currency (FCY) or Indian Rupees (INR) and include instruments such as:
- Commercial bank loans and syndicated loans
- Buyers’ credit and suppliers’ credit (beyond standard trade credit tenures)
- Securitized instruments such as floating-rate notes, fixed-rate bonds, and non-convertible, optionally convertible, or partially convertible debentures/preference shares
- Financial leases and Foreign Currency Convertible Bonds (FCCBs) / Foreign Currency Exchangeable Bonds (FCEBs)
ECBs may be raised under two routes:
- Approval Route: Proposals falling outside automatic-route parameters require prior RBI approval routed through the borrower’s AD Category-I bank.
Eligible Borrowers & Recognised Lenders
1. Who Can Raise ECB (Eligible Borrowers)?
Under the rationalized RBI framework, any person resident in India (other than an individual) incorporated or registered under a Central or State Act is eligible to raise ECB, provided borrowing is permitted under its governing legislation. This includes:
- Companies incorporated under the Private Limited Company framework of the Companies Act, 2013
- Limited Liability Partnerships (LLPs) and eligible registered entities permitted under applicable laws
- Port Trusts, Units in SEZs, SIDBI, and EXIM Bank
- Entities undergoing corporate insolvency resolution or restructuring, if expressly permitted under the approved resolution/restructuring plan
Note: Borrowers facing pending investigation, adjudication, or appeal by law enforcement agencies may still raise ECB without prejudice to the outcome, subject to full disclosure in Form ECB-1 / Revised Form ECB-1.
2. Who Can Lend (Recognised Lenders)?
Recognised lenders include:
- Any person resident outside India (subject to applicable anti-money laundering and jurisdiction norms)
- A branch outside India of an entity whose lending business is regulated by the RBI
- A financial institution or branch of a financial institution set up in an International Financial Services Centre (IFSC)
Key ECB Parameters: Limits, Maturity & Cost
Before executing an ECB agreement, borrowers must align commercial terms with RBI parameters—often alongside broader cross-border capital planning under FEMA & FDI Compliance:
| Parameter | Key Requirement |
| Borrowing Limit (Automatic Route) | Higher of (a) outstanding ECB up to USD 1 billion, or (b) total outstanding borrowing (external + domestic) up to 300% of net worth as per the last audited standalone balance sheet (exemption applies to entities regulated by financial sector regulators). |
| Minimum Average Maturity Period (MAMP) | Generally 3 years. Manufacturing sector borrowers may raise ECB with a MAMP between 1 and 3 years (subject to an outstanding ECB cap of USD 150 million under that window). Call/put options cannot be exercised before completing MAMP. |
| Cost of Borrowing | Under the 2026 rationalized regulations, rigid all-in-cost spread ceilings have been removed in favor of market-determined pricing aligned with prevailing arms-length/market standards. |
| Security Creation | Borrowers may create a charge on immovable assets, movable assets, financial securities, or issue corporate/personal guarantees in favor of the overseas lender or security trustee, subject to AD bank verification and NOC from existing domestic lenders where applicable. |
End-Use Restrictions: Where ECB Funds Cannot Be Used
While the RBI has liberalized end-use norms for genuine business expansion, working capital, and capital expenditure, ECB proceeds are strictly prohibited from being deployed in the following activities (Negative List):
- Real estate activities (excluding permitted integrated townships, industrial parks, SEZs, or eligible affordable housing projects as notified)
- Equity investment domestically (except permitted outbound/strategic investments expressly allowed under FEMA rules—distinct from equity inflows tracked under FCGPR Reporting – FDI Compliance)
- On-lending to other entities for any of the above prohibited purposes
Tip: Always verify your exact fund-deployment plan against the latest RBI Master Direction on External Commercial Borrowings before drawing down funds, as end-use deviations trigger FEMA contraventions.
Step-by-Step Form ECB Filing & Compliance Guide
Strict adherence to reporting timelines is mandatory under FEMA. Following the 2026 reporting updates, borrowers must manage three core filings through their AD Category-I bank:
Step 1: Corporate Approvals & Loan Agreement Execution
- Execute the definitive Loan Agreement containing clear terms on principal, interest, repayment schedule, and MAMP.
Step 2: File Form ECB-1 to Obtain the Loan Registration Number (LRN)
- What it is: The primary application submitted in duplicate to your designated AD Category-I bank to report complete details of the proposed ECB.
- When to file: Before any drawdown of loan proceeds.
- Outcome: Once verified and forwarded by the AD bank, the RBI allots a unique Loan Registration Number (LRN). No funds can be drawn down until the LRN is allotted.
Step 3: Drawdown & Parking of Funds
- Draw down funds only after receiving the LRN.
- Proceeds meant for rupee expenditure in India should be repatriated immediately and credited to a Rupee account with an AD bank in India. Funds meant for foreign-currency expenditure may be parked abroad in permitted liquid instruments until utilized.
Step 4: Report Changes via Revised Form ECB-1 (If Applicable)
- What it is: Used to report any mutually agreed modifications to original ECB parameters (such as changes in repayment schedule, borrower/lender details, or pending regulatory disclosures).
- Timeline: Within 7 calendar days from the end of the month in which the change takes effect.
Step 5: Monthly Transaction Reporting via Form ECB-2
- What it is: A mandatory monthly return reporting actual ECB drawdowns, utilization, debt servicing (principal, interest, and fees), and month-end outstanding balances, duly certified by a Practicing Company Secretary (PCS) or Chartered Accountant (CA).
- Timeline: Within 7 calendar days / 7 working days (as notified under applicable AD bank reporting schedules) from the close of every month—even if no transaction occurred during the month (Nil Return).
Penalties for Non-Compliance
Delayed or missed filings of Form ECB-1 or Form ECB-2 attract a Late Submission Fee (LSF) prescribed by the RBI. If the borrower fails to regularize the delay via LSF—or commits substantive violations such as breaching MAMP, exceeding borrowing limits, or violating end-use restrictions—the default becomes a FEMA contravention requiring compounding proceedings before the RBI.
For ongoing debt-servicing schedules, tax withholding checks such as Form 15CA & Form 15CB, and capital structuring support, many growing businesses leverage Virtual CFO Services from eAuditor Office.
FAQs
Yes. Obtaining an LRN from the RBI by submitting Form ECB-1 through your AD Category-I bank is strictly mandatory before the first drawdown. Receiving foreign loan funds without an LRN constitutes a FEMA violation.
Form ECB-1 is a one-time initial filing used to register the loan agreement with the RBI and obtain the LRN before drawdown (with Revised Form ECB-1 used if loan terms change later). Form ECB-2 is an ongoing monthly return filed throughout the life of the loan to report actual drawdowns, utilization, interest/principal repayments, and outstanding balances.
Under the rationalized ECB framework, eligible borrowers can utilize ECB for general corporate purposes, working capital, and repayment of domestic Rupee loans, provided the transaction satisfies the prescribed Minimum Average Maturity Period (MAMP) and does not fall under the prohibited negative list (such as real estate or capital market investments).
If Form ECB-2 is filed after the due date (7 days from month-end), the borrower can regularize the delay by paying the applicable Late Submission Fee (LSF) through the AD Category-I bank. Persistent non-filing or non-payment of LSF exposes the company and its officers to RBI adjudication and compounding penalties under FEMA.