After receiving foreign investment and allotting shares, an Indian company must report the issue to the Reserve Bank of India (RBI) in Form FC-GPR. Missing this step can lead to a late submission fee and, in unresolved cases, action under the Foreign Exchange Management Act, 1999 (FEMA).
The most important rule is simple: Form FC-GPR must generally be filed within 30 days from the date the equity instruments are issued. The deadline is linked to the issue or allotment date, not the date on which the foreign investment entered the company’s bank account.
This guide explains the FC-GPR filing deadline penalty, how the late submission fee is calculated, what happens when a delay continues beyond three years and how an Indian company can correct a missed filing.
What Is Form FC-GPR?
FC-GPR stands for Foreign Currency-Gross Provisional Return. An Indian company uses this form to report the issue of equity instruments to a person resident outside India when the investment is treated as foreign direct investment under the applicable rules.
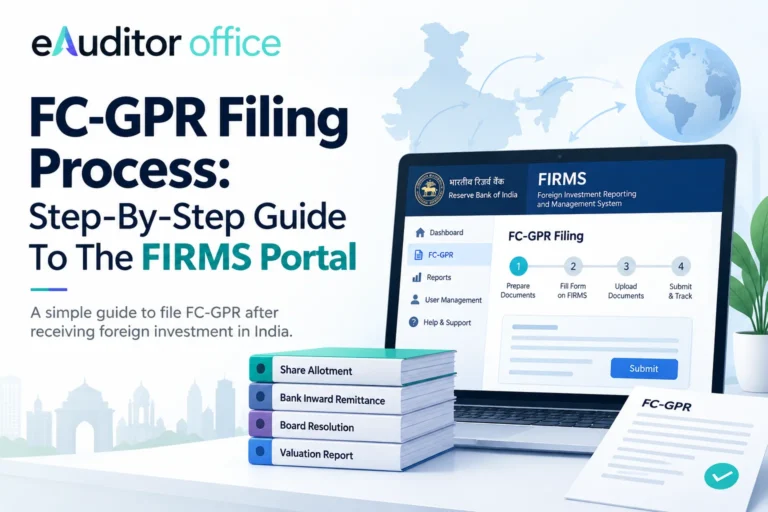
The filing is made through the Single Master Form on the RBI’s FIRMS portal. It records the investor, amount received, instruments issued, issue price and post-issue shareholding. The company’s Authorised Dealer Category-I bank reviews it.
FC-GPR applies to an issue of eligible equity instruments. A transfer of existing equity instruments between a resident and a non-resident is generally reported through Form FC-TRS instead. Choosing the wrong form can delay the reporting process and leave the correct transaction unreported.
What Is The FC-GPR Filing Deadline?
An Indian company must file Form FC-GPR no later than 30 days from the date it issues equity instruments to the non-resident investor. The issue date stated in the corporate records and supporting documents therefore matters.
There is a related but separate timeline. Equity instruments must generally be issued within 60 days from the date the company receives the investment consideration. If they are not issued within that period, the money must generally be refunded within 15 days after the 60-day period ends.
This creates a practical sequence:
- The company receives the foreign investment through a permitted banking channel.
- It completes the corporate approvals and issues the equity instruments within the applicable 60-day period.
- It files Form FC-GPR within 30 days from the issue date.
For example, if shares are allotted on 10 April, the FC-GPR period is counted from 10 April. The remittance date does not replace the allotment date when calculating this deadline.
Who Is Responsible For Filing FC-GPR?
The Indian investee company is responsible for filing. Its authorised representative usually submits the form, supported by its company secretary, chartered accountant and AD bank. The company should not assume that the investor or bank will file on its behalf.
This matters during Foreign Subsidiary Incorporation because a new subsidiary may receive capital before its internal compliance process is fully set up.
What Is The Penalty For Late FC-GPR Filing?
RBI permits an eligible reporting delay to be regularised by paying a Late Submission Fee (LSF). For FC-GPR, the current formula is:
LSF = ₹7,500 + (0.025% × A × n)
In this formula:
- A is the amount involved in the delayed report.
- n is the number of years of delay. The delay is rounded upward to the nearest month and expressed up to two decimal places.
- The fee is calculated for each return.
- The maximum LSF is limited to 100% of the amount involved.
These conditions come from RBI’s September 2022 circular introducing a uniform LSF calculation for FC-GPR and other FEMA reporting delays.
Consider a straightforward example. If an FC-GPR involving ₹1 crore is delayed by one year, the indicative calculation is:
₹7,500 + (0.025% × ₹1,00,00,000 × 1) = ₹10,000.
This is only an illustration. The company should confirm the final amount and payment process with its AD bank.
Is The Late Submission Fee Always Available?
No. The RBI circular states that the option to use LSF is available for up to three years from the original reporting due date. Paying LSF regularises the reporting delay; it does not cure a different FEMA breach.
For example, a delay in filing FC-GPR is not the same as issuing equity instruments late, failing to refund the consideration, breaching a sectoral cap or issuing shares at a price that does not comply with the applicable pricing rules. Those matters may require separate examination.
If a company neither files on time nor completes the delayed filing with LSF, it may face penal action under FEMA. For a delay older than three years or involving another contravention, seek case-specific advice from the AD bank and a FEMA professional. Further regularisation or compounding may be required.
What Happens After An LSF Advice Is Issued?
An LSF advice must be acted on promptly. RBI’s circular provides that if the advised amount is not paid within 30 days, the advice becomes null and void and a late payment will not be accepted against it.
If the company applies again for the same delay, the date of the fresh application becomes the reference date for calculating the period of delay. Waiting can therefore increase the value of n and may increase the fee.
An incomplete form can prolong the delay. Check all information, attachments and certifications before submission.
How To Regularise A Delayed FC-GPR Filing
First, confirm the remittance date, allotment date, amount, instrument type and original FC-GPR due date. Check the corporate approvals and identify whether the issue is limited to delayed reporting.
Next, speak with the AD bank that handled the remittance. Its document checklist and clarification requirements can affect processing time.
Prepare the FC-GPR with the required records, which may include remittance evidence, investor KYC, valuation support, board resolution, allotment details, company secretary certification and transaction declarations.
Follow the LSF process, pay the advised fee on time and retain the form, acknowledgement, advice, payment proof and bank communication.
Need Help Setting Up A Foreign-Owned Company In India?
Foreign investment reporting is easier when the share structure, entry route, valuation and post-incorporation filings are planned before funds are remitted. E-Auditor can support your Foreign Subsidiary Incorporation and coordinate the connected corporate and FEMA compliance steps. Speak with our team before the first capital remittance to avoid preventable filing delays.
How To Avoid FC-GPR Filing Delays
Create a compliance calendar as soon as the investment terms are finalised. Record the remittance date, the last date for issuing equity instruments and the FC-GPR due date separately. Do not combine them into one generic “FDI deadline.”
Before allotment, verify the authorised share capital, valuation, sectoral cap, entry route and approvals. After allotment, collect the signed certificates and banking records promptly.
Give one person ownership of the filing. That person should track it from remittance through final acknowledgement.
Get Your Foreign Investment Compliance Right From Day One
A missed filing can hold up future due diligence, fundraising and regulatory reviews. If you are planning Foreign Subsidiary Incorporation or have already missed an FC-GPR deadline, E-Auditor can help assess the transaction, prepare the filing and coordinate with the AD bank. Contact an E-Auditor for practical support based on your company’s facts.
Conclusion
The FC-GPR filing deadline is generally 30 days from the issue of equity instruments. If the company files late, the RBI may permit regularisation through LSF calculated as ₹7,500 plus 0.025% of the amount involved multiplied by the period of delay in years. That route is available only for a limited period and only addresses the reporting delay.
The safest approach is to track receipt, allotment and reporting as three connected but separate steps. When a deadline has already passed, act early, involve the AD bank and check whether any other FEMA issue exists before submitting the delayed return.
FAQs
No. Form FC-GPR is generally due within 30 days from the date the equity instruments are issued. The 60-day period for issuing instruments after receiving consideration is a separate requirement.
Yes. An eligible delayed filing may be submitted with the applicable Late Submission Fee. The LSF option is available for up to three years from the reporting due date, subject to the RBI rules and the facts of the case.
No. LSF deals with reporting delay. A late allotment, delayed refund, pricing breach, prohibited investment or sectoral non-compliance is a separate issue and may require a different remedy.
No. The formula contains a fixed fee of ₹7,500, and an unresolved reporting default remains a FEMA compliance issue regardless of whether the delay is short.
It is filed through the Single Master Form on the RBI’s FIRMS portal. The Indian company submits the form and its AD Category-I bank reviews it.